
Try CustomBooks™
for free
for free
No credit card needed

A Payment Plan is an arrangement that allows a customer to pay an amount owed through multiple scheduled payments instead of paying the entire balance at once. Businesses may use Payment Plans to manage customer collections, resolve overdue balances, and create a structured path for repayment.
Reading time: 8 minutes
Category: Accounts Receivable & Collections
Definition: A Payment Plan is an arrangement under which a customer pays an amount owed through a series of scheduled payments rather than paying the full balance in a single payment.
For example, suppose a customer owes:
$12,000
Instead of requiring the entire $12,000 immediately, the business and customer agree to four payments of:
$3,000 each
The Payment Plan might specify:
Payment Plans can be used in different circumstances.
A business may establish one when:
The specific legal, accounting, and contractual treatment depends on the arrangement and applicable requirements.
A Payment Plan does not necessarily eliminate the underlying Accounts Receivable.
Instead, it establishes a structured approach for collecting the amount owed.
Payment Plans can give businesses and customers a structured way to address balances that cannot or will not be paid in one payment.
For the business, a Payment Plan can help:
For the customer, a Payment Plan may make a large balance more manageable by dividing it into smaller scheduled payments.
However, a Payment Plan also changes the timing of Cash collection.
Instead of receiving:
$12,000 today
the business might receive:
$3,000 per month for four months
Management therefore needs visibility into both:
Total Accounts Receivable
and:
Expected timing of collections
Payment Plan structures vary, but a well-defined arrangement generally makes the repayment expectations clear.
Important information may include:
The amount owed when the Payment Plan is established.
Example:
Original balance: $20,000
The amount expected for each scheduled payment.
Example:
Monthly payment: $5,000
The number of installments required.
Example:
4 payments
The dates on which payments are expected.
For example:
September 15 — $5,000
October 15 — $5,000
November 15 — $5,000
December 15 — $5,000
The plan should identify which Invoice or invoices are covered by the arrangement.
This is particularly important if a customer has multiple Open Invoices.
The arrangement may specify how the customer is expected to pay.
Depending on the agreement, there may be:
Not every Payment Plan includes these provisions.
As payments are received, the business should be able to determine how much remains outstanding.
For example:
Original balance:
$20,000
Payment received:
$5,000
Remaining balance:
$15,000
Payment Plans can be structured in several ways depending on the customer, amount owed, and business agreement.
The balance is divided into equal payments.
For example:
Balance:
$12,000
Plan:
4 monthly payments of $3,000
This is one of the simplest structures to understand and track.
The customer pays different amounts on different dates.
For example:
$5,000 initially
$3,000 after 30 days
$2,000 after 60 days
This may be useful when the customer's expected Cash availability varies.
An overdue balance may be divided into several payments over a relatively short period.
For example:
Overdue Invoice:
$9,000
Plan:
$3,000 today
$3,000 in 30 days
$3,000 in 60 days
A customer may have several outstanding invoices.
For example:
INV-10025 — $5,000
INV-10082 — $8,000
INV-10110 — $7,000
Total outstanding:
$20,000
The business and customer may agree on a Payment Plan covering the combined balance.
The business should maintain clear records showing how payments under the plan are applied to the underlying invoices.
Example: Suppose a wholesale customer has three Open Invoices:
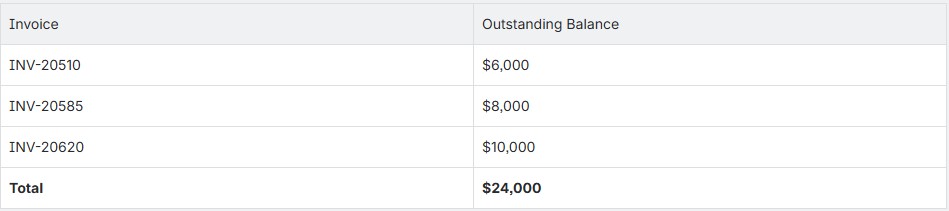
The customer is experiencing a temporary Cash Flow problem and cannot pay the entire:
$24,000
immediately.
The business agrees to a Payment Plan consisting of:
4 monthly payments of $6,000
The schedule is:
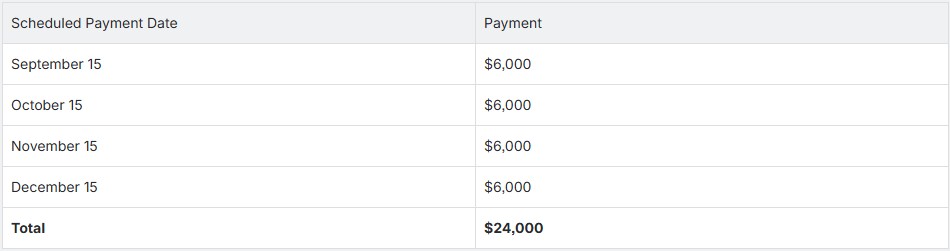
After the first $6,000 payment is received and appropriately applied:
Original balance: $24,000
Payment received: $6,000
Remaining balance: $18,000
The business continues tracking the remaining Accounts Receivable and scheduled payments.
If the customer misses the October payment, the Accounts Receivable team can follow the procedures established by the Payment Plan and the company's Collection Policy.
This is more structured than relying on an informal promise such as:
“We'll send you some money next month.”
Payment Plans can provide structure for collecting an outstanding balance, but they also create additional tracking requirements.
Common challenges include:
For example, suppose a customer owes:
$24,000
and agrees to:
$4,000 per month for six months
If the customer pays the first $4,000 but misses the next two payments, the existence of the Payment Plan does not eliminate the collection problem.
The business still has:
$20,000 outstanding
and needs to determine the appropriate next action under the Payment Plan and its Collection Policy.
A Payment Plan can change the expected timing of customer payments, but it does not necessarily change the historical age of the underlying Invoice.
Suppose an Invoice has:
Invoice Date: January 1
Due Date: January 31
Outstanding balance: $20,000
By April, the Invoice is significantly past due.
The business and customer then establish a Payment Plan for:
$5,000 per month for four months
The business should not automatically assume that establishing the plan makes the original January Invoice current.
The underlying receivable still originated from the earlier Invoice.
How the balance appears in an Aging Schedule or Accounts Receivable Aging Report depends on:
This distinction matters because management may want to know both:
How old is the underlying receivable?
and:
Is the customer currently complying with an agreed Payment Plan?
Those are different questions.
A useful AR process therefore preserves visibility into both the original Invoice history and the current collection arrangement.
A Collection Policy establishes the procedures a business uses to follow up on unpaid customer balances.
Payment Plans can be one tool within that process.
For example, a collection workflow might include:
Invoice issued
↓
Payment becomes due
↓
Payment becomes overdue
↓
Customer contacted
↓
Reason for nonpayment investigated
↓
Payment Plan considered where appropriate
↓
Scheduled payments monitored
↓
Additional collection action if the arrangement is not followed
A Payment Plan does not need to be offered to every customer or every overdue account.
Businesses may consider factors such as:
A consistent process can help prevent Payment Plans from becoming informal extensions of credit without appropriate review.
When a scheduled payment is missed, the appropriate response depends on the Payment Plan agreement and the company's Collection Policy.
A business may need to:
For example:
Original balance:
$20,000
Four-payment plan:
$5,000 per month
First payment received:
$5,000
Second payment missed:
$5,000
Remaining Accounts Receivable:
$15,000
The missed installment is a signal requiring follow-up, but the appropriate next step depends on the agreement and the customer's circumstances.
Businesses should avoid repeatedly restructuring Payment Plans without understanding whether the customer is realistically able to satisfy the obligation.
Establishing a Payment Plan does not automatically mean the customer's outstanding Accounts Receivable disappears.
The business still needs to track the amount owed and properly apply payments as they are received.
Suppose the customer owes:
$30,000
and agrees to:
6 monthly payments of $5,000
Before the first payment:
Outstanding AR: $30,000
After the first applicable $5,000 payment:
Remaining AR: $25,000
After the second:
Remaining AR: $20,000
and so forth, subject to any other transactions or adjustments.
The business may need to track:
This creates a useful collection path:
Open Invoice → Payment Plan → Scheduled Payment → Payment Received → Reduced Accounts Receivable
The specific presentation of a Payment Plan within an Aging Schedule or Accounts Receivable Aging Report can depend on the accounting system, reporting configuration, and treatment of the underlying receivable.
A Payment Plan should therefore not automatically be assumed to reset the age of the original Invoice.
Payment Plans and Payment Terms both relate to when customers pay, but they serve different purposes.
Payment Terms establish the conditions under which payment for a transaction is expected.
Examples include:
For example:
Invoice Date: September 1
Payment Terms: Net 30
Due Date: October 1
The customer is expected to pay the Invoice according to those terms.
A Payment Plan establishes a schedule for paying an amount through multiple payments.
For example:
Outstanding balance:
$12,000
Payment Plan:
$3,000 per month for four months
Payment Terms → Define when payment for the transaction is expected
Payment Plan → Defines a schedule for paying an amount through multiple payments
A Payment Plan may be established from the beginning of a transaction, or it may be negotiated later to address an outstanding or overdue balance.
The exact structure depends on the agreement.
A partial payment and a Payment Plan are related concepts, but they are not necessarily the same thing.
A partial payment occurs when a customer pays less than the full outstanding balance.
For example:
Invoice:
$10,000
Payment:
$4,000
Remaining balance:
$6,000
The $4,000 is a partial payment.
A Payment Plan is a structured arrangement specifying how the balance will be paid over time.
For example:
Invoice:
$10,000
Payment Plan:
$2,500 per month for four months
Each $2,500 payment is a partial payment toward the total balance, but the overall arrangement is the Payment Plan.
Partial Payment → An individual payment that does not satisfy the entire balance
Payment Plan → An agreed schedule for multiple payments
A customer can make a partial payment without having a formal Payment Plan.
A Payment Plan and a Payment Terms Discount both affect customer payments, but they serve very different purposes.
A Payment Plan allows an amount to be paid through multiple scheduled payments.
Example:
Balance: $12,000
4 monthly payments: $3,000 each
A Payment Terms Discount provides a financial incentive for a customer to pay according to specified early-payment terms.
For example:
2/10, Net 30
can generally mean that an eligible customer may take a 2% Discount if payment is made within 10 days, while the full amount is otherwise due within 30 days, subject to the applicable terms.
Payment Plan → Spreads payment across multiple scheduled payments
Payment Terms Discount → Encourages qualifying early payment by offering a Discount
One generally extends the timing of collection across installments, while the other is intended to encourage earlier collection.
A Payment Plan and a Write-Off represent very different approaches to an outstanding receivable.
Under a Payment Plan, the business still expects to collect the agreed amount according to a repayment schedule.
For example:
Outstanding balance:
$10,000
Payment Plan:
5 payments of $2,000
The business continues attempting to collect the balance.
A Write-Off generally involves removing an amount from Accounts Receivable when it is determined to be uncollectible or otherwise meets the applicable criteria for write-off.
Payment Plan → Business continues pursuing collection according to an agreed schedule
Write-Off → Receivable is removed from Accounts Receivable according to the applicable accounting treatment
A customer experiencing temporary Cash Flow difficulty does not automatically mean the receivable should be written off.
Similarly, creating a Payment Plan does not guarantee that the full balance will ultimately be collected.
The business should continue evaluating collectibility as circumstances change.
Effective Payment Plan management requires visibility into both the agreement and the underlying Accounts Receivable.
Businesses can consider the following practices:
Record the agreed:
If the plan covers multiple invoices, maintain visibility into which receivables are included.
For example:
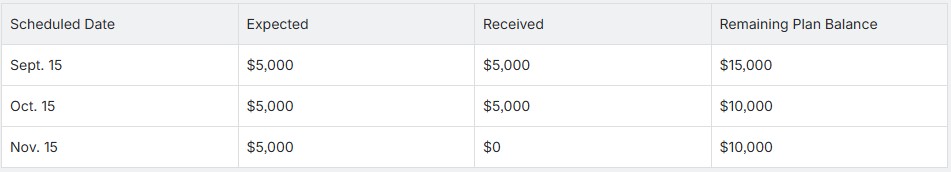
This immediately shows that the November payment was missed.
Payments should be applied according to the applicable customer and Invoice records.
Incorrect application can distort:
After each payment, verify the amount still owed.
Do not lose visibility into the original Invoice Date, Due Date, and aging simply because a Payment Plan was established.
Missed or partial scheduled payments should trigger appropriate review rather than remaining unnoticed.
Managing customer repayment arrangements requires accurate information about the receivables underlying the plan.
Accounting and ERP software can help businesses maintain information such as:
This information helps Accounts Receivable teams determine:
What does the customer owe?
Which invoices make up the balance?
What has already been paid?
What remains outstanding?
How old are the underlying receivables?
For example:
Customer → Invoice → Accounts Receivable → Payment Arrangement → Customer Payment → Remaining Balance
CustomBooks connects customer invoicing, Accounts Receivable, payments, sales, banking, and accounting information.
This connected transaction history can help businesses maintain visibility into outstanding customer balances and payments when managing collection arrangements.
The page should not imply that CustomBooks provides specialized automated Payment Plan functionality unless that capability is separately verified.
To better understand Payment Plans and how they fit into Accounts Receivable management, these related glossary terms may also be helpful:
A Payment Plan is an arrangement that allows a customer to pay an amount owed through multiple scheduled payments instead of paying the entire balance at once.
The arrangement typically establishes payment amounts, dates, and other applicable terms.
No.
Payment Terms establish when payment for a transaction is expected.
A Payment Plan establishes a schedule for paying an amount through multiple payments.
For example:
Net 30 → Payment Terms
Four monthly payments of $2,500 → Payment Plan
Not necessarily.
A Payment Plan establishes a new repayment arrangement, but it does not automatically change the historical age of the underlying Invoice.
How the receivable appears in an Aging Schedule depends on the underlying records, aging methodology, and system configuration.
No.
A partial payment is an individual payment that is less than the entire outstanding balance.
A Payment Plan is the structured arrangement governing multiple scheduled payments.
Individual payments made under a Payment Plan may themselves be partial payments toward the total balance.
The appropriate response depends on the Payment Plan agreement and the company's Collection Policy.
The business may contact the customer, review the account, revise the arrangement where appropriate, escalate collection activity, or reassess the collectibility of the remaining receivable.
Managing Accounts Receivable requires more than knowing the total amount customers owe.
Businesses also need to understand:
When a Payment Plan is involved, visibility into the underlying transaction history becomes even more important.
The process can look like:
Customer → Invoice → Accounts Receivable → Collection → Payment Arrangement → Payment → Remaining Balance
For product-based businesses, customer sales and Accounts Receivable may also be connected to Inventory and fulfillment activity.
CustomBooks connects sales, Inventory, customer invoicing, Accounts Receivable, payments, banking, and accounting information, helping businesses maintain greater visibility across customer transactions and outstanding balances.
Schedule a CustomBooks demo to see how connected accounting and operational information can help simplify Accounts Receivable management.


