
Try CustomBooks™
for free
for free
No credit card needed

A Pro Forma Invoice is a preliminary document that provides a customer with expected transaction details—such as products, quantities, prices, and terms—before a final Invoice is issued. It can help buyers and sellers review and confirm the expected transaction before final billing.
Reading time: 8 minutes
Category: Invoicing & Sales
Definition: A Pro Forma Invoice is a preliminary sales document that provides information about an anticipated transaction before the seller issues the final commercial Invoice.
It may show information such as:
Unlike a standard Invoice, a Pro Forma Invoice generally serves as an informational or preliminary document rather than the final billing document establishing the seller's Accounts Receivable.
For example, suppose a distributor expects to sell a customer:
500 units at $40 each
The seller may provide a Pro Forma Invoice showing:
Expected merchandise total: $20,000
plus any applicable expected shipping, taxes, discounts, or other charges.
The customer can review the document before the transaction is finalized.
Once the transaction reaches the appropriate billing stage, the seller may issue the final Invoice reflecting the actual transaction.
The basic sequence can therefore look like:
Customer Inquiry/Order → Pro Forma Invoice → Transaction Confirmation/Fulfillment → Final Invoice
The exact role and legal significance of a Pro Forma Invoice can vary depending on the transaction, agreement, industry, and jurisdiction.
Pro Forma Invoices can help buyers and sellers understand the expected financial details of a transaction before final billing occurs.
They can help businesses:
For example, a customer planning a large purchase may need documentation showing the anticipated:
Products + Quantities + Prices + Shipping + Expected Total
before approving the purchase internally.
A Pro Forma Invoice can provide that information without necessarily creating the same accounting effect as the final Invoice.
This distinction is important:
Pro Forma Invoice ≠ automatically an Accounts Receivable Invoice
The exact format varies, but a Pro Forma Invoice may contain many of the same commercial details that eventually appear on the final Invoice.
This may include:
The document may identify:
The document should be clearly identifiable as a:
Pro Forma Invoice
rather than being confused with the final Invoice.
It may also contain its own reference number.
A Pro Forma Invoice may include the date on which the document was prepared or issued.
The document may list:
Applicable anticipated Discounts may be shown.
Expected shipping, freight, handling, or other applicable charges may be included.
Expected taxes may be shown where applicable.
The document may communicate anticipated payment requirements or Payment Terms.
The Pro Forma Invoice generally provides an estimated or anticipated transaction total based on the information available when it is created.
The final Invoice may differ if transaction details change before billing.
Businesses may use Pro Forma Invoices in several situations.
A customer may want to review the expected transaction details before approving the purchase.
In some transactions, a seller may provide a Pro Forma Invoice so the customer has documentation describing the anticipated purchase before making an agreed advance payment.
The seller and customer may use the document to confirm:
before final billing.
A customer's purchasing or finance team may need documentation before approving an expenditure.
Pro Forma Invoices are also commonly used in international trade to communicate anticipated transaction information and may support certain customs, import, financing, or documentation processes.
However, documentary requirements vary by country and transaction, so businesses should verify the requirements applicable to the specific shipment.
A Pro Forma Invoice can provide a preview of the expected transaction while allowing the final Invoice to reflect the completed or billable transaction.
Example: Suppose a wholesale distributor is preparing a large order for a retailer.
The expected transaction is:
Product: Item A
Quantity: 1,000 units
Price: $25 per unit
Expected merchandise amount:
1,000 × $25 = $25,000
Expected shipping:
$1,500
Simplified expected total:
$26,500
The distributor sends a Pro Forma Invoice showing:
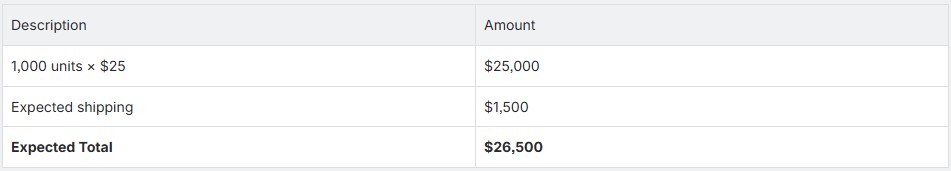
The customer reviews and approves the expected transaction.
Before final billing, the actual shipping charge becomes:
$1,650
The final Invoice may therefore show:
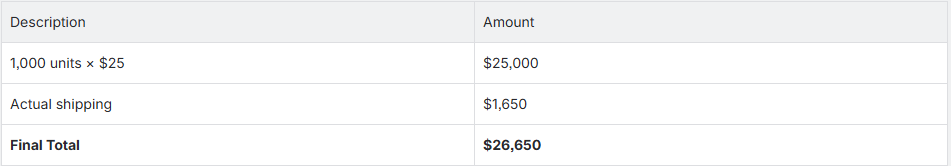
The example illustrates an important characteristic:
The final Invoice does not necessarily have to equal the Pro Forma Invoice if transaction details legitimately change before final billing.
Because a Pro Forma Invoice can look similar to a standard Invoice, businesses and customers may misunderstand its purpose or treat it as a final billing document.
Common challenges include:
For example, suppose a business sends:
Pro Forma Invoice: $25,000
The customer later receives:
Final Invoice: $26,000
If both documents are incorrectly treated as Open Invoices, the customer's account could appear to owe:
$51,000
instead of:
$26,000
Clear document classification helps prevent this type of error.
Generally, a Pro Forma Invoice should not automatically be treated as the final customer Invoice that creates or documents an Accounts Receivable balance.
Its primary purpose is to communicate information about an anticipated transaction before final billing.
For example:
Pro Forma Invoice:
$30,000
does not necessarily mean:
Accounts Receivable = $30,000
The final accounting effect depends on the underlying transaction and applicable accounting requirements.
Once the transaction reaches the appropriate billing stage and a final Invoice is issued, the applicable amount may become part of Accounts Receivable.
A simplified process might look like:
Pro Forma Invoice → Customer Approval → Fulfillment → Final Invoice → Accounts Receivable
This distinction helps prevent preliminary sales documents from being confused with actual customer receivables.
A Pro Forma Invoice and a standard Invoice can look similar, but they generally serve different purposes.
A Pro Forma Invoice is generally a preliminary document describing an anticipated transaction.
It can help the buyer and seller review expected:
An Invoice is the billing document issued for an actual transaction according to the seller's invoicing process.
When applicable, it can establish or document an amount owed by the customer and become part of Accounts Receivable.
Pro Forma Invoice → Preliminary information about an anticipated transaction
Invoice → Billing document for the actual transaction
A Pro Forma Invoice should therefore not automatically be treated as an Open Invoice or Accounts Receivable balance merely because it resembles an Invoice.
A Pro Forma Invoice and a Quote can both communicate expected pricing before final billing, so the terms are sometimes confused.
A Quote generally communicates proposed pricing and transaction terms to a prospective customer.
It may be part of the sales process before the customer commits to the transaction.
A Pro Forma Invoice generally presents anticipated transaction details in an Invoice-like format before the final Invoice is issued.
It may be used when the transaction is more developed and the customer needs a formal preliminary document showing expected amounts.
A simplified distinction is:
Quote → Proposed pricing or sales offer
Pro Forma Invoice → Preliminary Invoice-like document describing an anticipated transaction
However, business practices and terminology vary, and the exact legal effect of either document depends on its contents and the surrounding agreement.
A Pro Forma Invoice and a Purchase Order come from different sides of a transaction.
The seller generally provides the Pro Forma Invoice to communicate anticipated transaction details.
The buyer generally issues a Purchase Order (PO) to document an order for goods or services.
A seller provides:
Pro Forma Invoice: $50,000
The buyer reviews the information and issues:
Purchase Order: PO-10582
The seller then fulfills the order and, at the appropriate billing stage, issues:
Final Invoice: INV-20875
A simplified document flow might therefore be:
Seller Pro Forma Invoice
↓
Buyer Purchase Order
↓
Fulfillment/Receiving
↓
Seller Final Invoice
The exact sequence can vary depending on the business process.
Pro Forma Invoice → Preliminary transaction document generally provided by the seller
Purchase Order → Purchasing document generally issued by the buyer
A Pro Forma Invoice and a Sales Order can both contain information about an expected sale, but they generally serve different purposes.
A Pro Forma Invoice communicates anticipated financial and transaction information to the customer.
It may include:
A Sales Order is an internal or customer-facing sales document used to record and manage an accepted customer order within the seller's sales process.
It can help the business manage:
A business may first provide:
Pro Forma Invoice: $40,000
After the customer confirms the transaction, the seller may maintain:
Sales Order: SO-10852
The order is fulfilled and the seller later issues:
Invoice: INV-20985
A possible workflow is:
Pro Forma Invoice → Customer Confirmation → Sales Order → Fulfillment → Final Invoice
The exact sequence depends on the business process.
Pro Forma Invoice → Communicates anticipated transaction and pricing information
Sales Order → Records and manages the customer order within the sales process
The distinction between a Pro Forma Invoice and a Commercial Invoice is particularly important in international trade.
A Pro Forma Invoice generally provides preliminary information about an anticipated transaction before final billing.
It may help communicate:
A Commercial Invoice generally documents the actual commercial transaction and may be used as part of international shipping and customs documentation.
It can contain information needed for purposes such as:
Pro Forma Invoice → Preliminary information about the anticipated transaction
Commercial Invoice → Documentation of the actual commercial transaction
Specific customs and trade-document requirements vary by country, shipment, and transaction.
Businesses involved in international trade should therefore confirm the documentation requirements applicable to the particular transaction rather than assuming a Pro Forma Invoice can substitute for a required Commercial Invoice.
In some transactions, a business may provide a Pro Forma Invoice before requesting or receiving an agreed advance payment.
For example:
Expected transaction:
$50,000
Required advance:
30%
Expected advance payment:
$15,000
The seller may provide a Pro Forma Invoice describing the expected transaction so the customer has documentation supporting the requested advance.
However, receiving Cash does not automatically mean the entire amount represents Revenue at that moment.
The accounting treatment depends on the underlying transaction and applicable accounting requirements.
A simplified operational sequence might be:
Pro Forma Invoice → Customer Advance Payment → Fulfillment → Final Invoice → Final Settlement
Suppose the customer pays:
$15,000 in advance
and the final Invoice is:
$50,000
The remaining amount to be settled would be:
$35,000
assuming the $15,000 advance is appropriately applied and there are no other adjustments.
The Pro Forma Invoice helps communicate the anticipated transaction, while the accounting system should separately maintain the appropriate records for the payment and final transaction.
A Pro Forma Invoice does not, by itself, automatically mean Revenue should be recognized.
Revenue recognition depends on:
For example, a business might issue a:
$100,000 Pro Forma Invoice
before fulfilling the customer order.
The existence of that preliminary document alone does not necessarily mean:
Revenue = $100,000
Similarly, receiving an advance payment following a Pro Forma Invoice does not automatically mean the entire advance should immediately be recognized as Revenue.
The accounting treatment depends on the underlying obligation and applicable accounting requirements.
The key distinction is:
Pro Forma Invoice → Preliminary commercial document
Revenue recognition → Accounting determination
Businesses should therefore avoid using the Pro Forma Invoice itself as the sole trigger for Revenue recognition.
Once the transaction reaches the appropriate billing stage, the business can prepare the final Invoice using the actual transaction information.
A typical process may include:
The seller provides anticipated information such as:
The customer may:
The business records or updates the applicable Sales Order or other transaction record.
The business provides the applicable goods or services according to the transaction.
For a product-based business, this can involve:
The business verifies actual:
The final Invoice reflects the appropriate billable transaction.
When applicable, the final Invoice establishes or documents the amount owed in Accounts Receivable.
The complete process may therefore look like:
Pro Forma Invoice → Customer Approval → Sales Order → Fulfillment → Final Invoice → Accounts Receivable → Payment
The final Invoice should reflect the actual billable transaction rather than blindly copying preliminary information from the Pro Forma Invoice.
Clear Pro Forma Invoice practices can reduce confusion between preliminary sales information and final billing.
The document should prominently indicate:
PRO FORMA INVOICE
so customers and employees do not mistake it for the final Invoice.
Maintain a reference number or other identifier that allows the Pro Forma Invoice to be located and connected to the subsequent transaction.
Include accurate customer information.
Clearly describe anticipated:
If transaction details are not yet final, avoid creating the impression that preliminary amounts cannot change.
Communicate relevant expected:
Do not automatically treat a Pro Forma Invoice as an Open Invoice simply because the document resembles a final Invoice.
Maintain a traceable relationship among:
Pro Forma Invoice → Sales Order/Purchase Order → Final Invoice
where applicable.
Before issuing the final Invoice, verify actual transaction information rather than assuming every Pro Forma amount remains unchanged.
Businesses may use multiple documents before a customer transaction reaches final billing.
Depending on the workflow, these can include:
Maintaining relationships among these records helps prevent duplicate entry and makes transactions easier to trace.
For a product-based business, the operational flow may include:
Customer → Sales Order → Inventory → Fulfillment → Invoice → Accounts Receivable → Payment
Accounting and ERP software can help businesses maintain information such as:
CustomBooks connects sales, Inventory, fulfillment-related transaction information, customer invoicing, Accounts Receivable, payments, and accounting.
This connected structure can help businesses maintain visibility as a transaction moves from sales activity through fulfillment, billing, and collection.
The page should not claim that CustomBooks offers a dedicated Pro Forma Invoice workflow or automatic Pro Forma-to-Invoice conversion unless that functionality has been specifically verified.
To better understand Pro Forma Invoices and how they fit into the sales-to-payment process, these related glossary terms may also be helpful:
A Pro Forma Invoice is a preliminary document that provides information about an anticipated transaction before the final Invoice is issued.
It may show expected products, quantities, prices, Payment Terms, shipping, and transaction totals.
No.
A Pro Forma Invoice generally provides preliminary information about an anticipated transaction.
A standard Invoice is the billing document for the actual transaction and, when applicable, becomes part of Accounts Receivable.
A Pro Forma Invoice may be used to communicate an advance-payment requirement or other expected payment arrangement, but its role depends on the underlying transaction and agreement.
It should not automatically be treated as equivalent to a final Invoice merely because it shows an amount.
Generally, a Pro Forma Invoice should not automatically be treated as the final Invoice creating or documenting an Accounts Receivable balance.
The appropriate accounting treatment depends on the underlying transaction and applicable accounting requirements.
Yes.
The final Invoice may differ if legitimate transaction details change before final billing.
For example, actual:
may differ from the preliminary amounts shown on the Pro Forma Invoice.
For product-based businesses, customer billing is often the result of a much larger operational process.
The transaction may move through:
Customer → Order → Inventory → Fulfillment → Invoice → Accounts Receivable → Payment
Before the final Invoice, businesses may also need to manage preliminary sales information, customer approvals, Purchase Orders, and other transaction documents.
When sales, Inventory, fulfillment, invoicing, and accounting information live in disconnected systems, teams may spend additional time re-entering information and tracing transactions.
CustomBooks connects sales, Inventory, customer invoicing, Accounts Receivable, payments, and accounting information, helping businesses maintain greater visibility across the sales-to-cash lifecycle.
Schedule a CustomBooks demo to see how connected accounting and operational workflows can help simplify sales, invoicing, Inventory, and Accounts Receivable management.


